What ESOP Stands For?
ESOP stands for Employee Stock Option Plan. It gives you the right to buy company shares at a predetermined fixed.
You receive a right to purchase shares under specific conditions, and the financial value of that right depends on what happens through vesting, exercise, ownership, and liquidity.
ESOP is four words, and each one tells you something important about what you are receiving.
The practical takeaway is simple. An ESOP grant gives you a right to buy shares. Exercise is the point at which that right becomes share ownership.Hissa helps companies put these ESOP terms into practice by managing grants, employee equity workflows, exercise, tax support, and liquidity across the equity lifecycle.
Employee Stock Option Plan vs Employee Stock Ownership Plan
The acronym ESOP appears in different contexts, so the distinction matters when you are researching equity compensation or reading information from outside India.
| Term | Common context | What it usually means |
|---|---|---|
| Employee Stock Option Plan | India, particularly startups and private companies | A right granted to eligible employees to buy company shares later at a fixed exercise price, subject to vesting and exercise |
| Employee Stock Ownership Plan | U.S. search results and employee ownership content | An employee ownership or retirement-benefit structure governed by U.S. rules and plan design |
If your offer or grant comes from an Indian company, ESOP generally refers to Employee Stock Option Plan. Your company's plan document and grant letter provide the specific terms that apply to you.
The Most Common ESOP Misconceptions
ESOP questions often become important when an employee receives a grant, approaches exercise, considers resignation, or starts looking for a way to sell the resulting shares. A few distinctions make those decisions easier to understand.
What to Check in Your ESOP Grant Letter
Your grant letter gives you the practical terms behind the equity described in your offer. Read it alongside the ESOP plan before accepting the grant, exercising options, resigning, or planning a sale.
- Number of options granted: The total number of options covered by the grant
- Strike price or exercise price: The price payable per share when you exercise
- Grant date: The date associated with the grant
- Vesting schedule: The timeline under which your options become exercisable
- Cliff period: The initial service period before options begin to vest
- Exercise window: The period during which vested options can be exercised
- Post-resignation exercise window: The period available after you leave the company
- Transfer restrictions: Conditions that apply when you transfer or sell exercised shares
- Buyback or liquidity rights: Terms governing company-led or approved liquidity events
- Change-of-control terms: Treatment of your options during an acquisition or similar event
- Tax responsibility: How and when tax obligations are handled at exercise and sale
If a clause affects your money and the wording feels unclear, ask HR or the finance team for an explanation. A company secretary or qualified tax professional can help clarify legal or tax-specific questions.
THREE NUMBERS TO FIND FIRST
Start with your strike price, vested option count, and post-resignation exercise window. These three figures tell you how much you may need to pay and how much time you have to act.
Who Is Eligible for ESOPs in India?
ESOP eligibility depends on the company's scheme and the rules that apply to the company. Unlisted companies primarily operate under the Companies Act, 2013 and related rules, while listed companies also follow SEBI's share-based employee benefit framework.
Common eligible categories include:
- Full-time employees: This can include Indian and foreign nationals working for the company, subject to the plan
- Directors: Certain directors can qualify, subject to applicable exclusions
- Employees of group companies: The scheme can extend eligibility to employees of specified group entities
Common exclusions include:
- Independent directors: They are generally excluded under the applicable framework
- Promoters and specified founder categories: Eligibility can be restricted based on applicable ownership thresholds
- Categories excluded by the ESOP scheme: Your company's plan can define additional eligibility conditions
Your grant letter confirms whether you have received an ESOP grant and sets out the terms attached to it.
For listed companies, SEBI's Share Based Employee Benefits and Sweat Equity Regulations provide the relevant framework. The current regulations were last amended in September 2025.
The Five Stages in ESOPs: From Grant to Cash
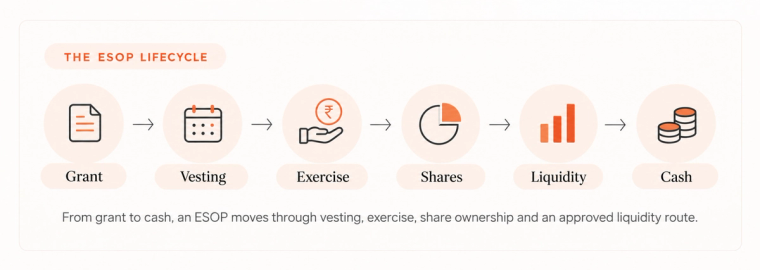
An ESOP moves through five distinct stages before an employee can turn equity into cash. Each stage changes what you own, what you can do with it, and what it may cost.
1. Grant
A grant is the point at which the company awards you a specified number of options at a defined exercise price and grant date.
At this stage:
- You receive options
- The vesting clock begins
- You generally have no exercise payment to make
The grant letter records the commercial terms you need to track.
2. Vesting
Vesting is the process through which you earn the right to exercise your options.
A common structure uses a one-year cliff followed by additional vesting over several years. Your company's schedule can differ, so use your grant letter as the source for your actual vesting dates.
3. Exercise
Exercise is the point at which you use your vested options to buy shares.
You may need to pay:
- The strike price
- Applicable perquisite tax
Exercise also has a deadline. The plan defines how long you have to exercise vested options, including the period available after you leave the company.
4. Holding
Holding begins after exercise and share allotment.
You now hold shares in the company, subject to the rights and restrictions attached to those shares. In a private company, selling those shares generally requires an approved route and compliance with transfer restrictions.
For tax purposes, the capital gains holding period for unlisted shares generally starts from acquisition. Current tax rules determine the applicable treatment.
5. Liquidity and Sale
Liquidity is the stage at which your shares can be converted into cash.
Possible routes include:
- Company buyback
- Secondary sale
- Merger or acquisition
- IPO
- Approved ESOP liquidity transaction
The sequence matters. Grant gives you options. Vesting makes them exercisable. Exercise gives you shares. Liquidity creates a route to cash.
What Does Exercising Actually Cost for ESOPs?
Exercising ESOPs can create two separate cash requirements at the same time.
- Strike price: The amount you pay the company for the shares
- Perquisite tax: The tax arising from the difference between the applicable fair market value and the amount you pay
The Income Tax Department states that the taxable perquisite value for ESOPs is based on the fair market value at exercise, less the amount recovered from the employee. For unlisted shares, the applicable fair market value is determined under the prescribed valuation rules.
Worked Example
Assume an employee has 5,000 vested options and a strike price of ₹10 per option.
The fair market value is ₹250 per share on the exercise date.
| Item | Calculation | Amount |
|---|---|---|
| Strike price payable | ₹10 × 5,000 options | ₹50,000 |
| FMV on exercise date | ₹250 per share | ₹250 |
| Perquisite value | (₹250 − ₹10) × 5,000 | ₹12,00,000 |
| Illustrative tax at 30% plus 4% cess | 31.2% × ₹12,00,000 | ₹3,74,400 |
| Total cash required | Strike price + illustrative tax | ₹4,24,400 |
In this example, the employee needs ₹4,24,400 before receiving proceeds from a later sale.
Your actual tax liability depends on your income, applicable tax regime, surcharge, cess, and the tax rules in force when you exercise. A qualified tax professional can calculate the amount applicable to your situation.
Eligible employees of qualifying startups can also have access to deferred payment of ESOP perquisite tax under the applicable provisions. The Income Tax Department currently describes this as a deferral linked to specified events, including the sale of shares and cessation of employment.
How Are ESOPs Taxed in India?
ESOP taxation generally involves two separate events. The first happens when you exercise and receive shares. The second happens when you sell those shares.
- At exercise: The difference between the applicable fair market value and the exercise price can be treated as a taxable perquisite
- At sale: Any further increase or decrease in value can be considered for capital gains tax
The Income Tax Department confirms that the exercise-stage perquisite is based on the fair market value of the shares on the exercise date less the amount paid by the employee. A later transfer of the shares can create capital gains.
| Event | What is taxed | Tax treatment |
|---|---|---|
| Exercise | FMV minus strike price | Perquisite under salary income |
| Sale after a short holding period | Sale price minus the relevant acquisition value | Short-term capital gains under applicable rules |
| Sale after the long-term holding period | Sale price minus the relevant acquisition value | Long-term capital gains under applicable rules |
For unlisted shares, the holding period and applicable capital gains rules affect the final tax calculation. Tax rates and thresholds can change, so verify the current rules before exercising or selling.
TWO TAX EVENTS
Exercise and sale are separate tax events. The first looks at the value created between the exercise price and applicable FMV. The second looks at the further gain or loss when you sell.
Read more: How Are ESOPs Taxed in India? Guide for Employees
Plan-Specific Terms, Dilution, and Other Equity Instruments
Your ESOP plan contains terms that can materially affect the value and usability of your equity. The same grant size can have very different practical implications under different plan terms.
- Cliff: The initial service period before options begin to vest
- Acceleration: Faster vesting triggered by specified events such as an acquisition
- Transfer restrictions: Conditions governing the sale or transfer of exercised shares
- Buyback pricing: The price and process used if the company offers to repurchase shares
- Dilution: Your percentage ownership can change when the company issues additional shares
- Termination for cause: Plan rules can provide different treatment for resignation, termination, death, or disability
It also helps to distinguish ESOPs from other equity-linked instruments.
- RSUs: Units that can convert into shares on vesting or settlement, depending on the plan
- SARs: Rights linked to the increase in share value, often settled without issuing the underlying shares
- Phantom stock: A cash-settled benefit linked to company or share value that does not create share ownership
The legal terms in the plan document carry more weight than the shorthand used in an offer letter.
Five Paths to Liquidity for ESOPs (Cash-Out)
An IPO provides one route to liquidity, while private-company employees can encounter several other routes during the life of their equity.
1. IPO
An IPO can create a public market for the company's shares after listing. Lock-ups and other selling restrictions can still apply.
The timing depends on the company's plans, regulatory requirements, market conditions, and execution of the listing process.
2. Company Buyback
A company buyback occurs when the company repurchases eligible shares from employees.
The company sets the process, eligibility conditions, pricing, and participation window. Board and regulatory requirements also apply.
3. Secondary Sale During a Funding Round
During some funding rounds, incoming investors purchase employee shares alongside their primary investment in the company.
Availability depends on:
- Investor appetite
- Company and board approval
- Transfer restrictions
- Shareholder agreement and ESOP terms
4. Dedicated ESOP Secondary Fund
A dedicated ESOP secondary fund can purchase eligible employee shares using its own investment capital.
This route can provide liquidity before an IPO when the company and fund approve the transaction and the relevant transfer conditions are met.
Hissa's liquidity offering is one example. The Hissa Fund is a $35 million SEBI-registered Category II Alternative Investment Fund, registration IN/AIF2/23-24/1439.
5. Merger or Acquisition
An acquisition can result in shareholders receiving cash, shares, or another form of consideration. The transaction documents determine the exact treatment.
Check your grant letter and plan for:
- Change-of-control provisions
- Acceleration provisions
- Treatment of vested options
- Treatment of unvested options
Inc42 reported that 12 Indian startups ran ESOP buyback programmes in 2025, with more than 9,265 employees receiving over ₹1,409 crore in aggregate value. The figure illustrates the scale of company-led liquidity events while also showing why the availability of a specific programme matters to individual employees.
Exercise Versus Wait: A Practical Scorecard
The decision to exercise depends on your cash requirement, timeline, tax exposure, and view of the company's future value. A low strike price is one data point among several.
| Question | Why it matters |
|---|---|
| How much cash is required today? | You may need funds for the strike price and tax before receiving sale proceeds |
| How long is your exercise window? | A short post-resignation window can create an immediate decision |
| How reliable is the FMV? | Exercise-stage tax depends on the applicable FMV |
| When might liquidity happen? | An approved liquidity route determines how soon shares can become cash |
| How concentrated is your wealth? | A large holding in one private company can increase concentration risk |
| What happens if the company value falls? | A later sale price can fall below the value used for exercise-stage tax |
A useful starting point is to calculate the cash required today and compare it with your exercise deadline. Then consider the company's potential liquidity routes and your broader financial position.
What Happens to Your ESOPs When You Resign?
Resignation can change the timeline attached to your vested and unvested options.
Unvested options are typically forfeited when employment ends, subject to the specific provisions of your plan. Vested options can remain exercisable for the period stated in the plan.
The post-resignation exercise window can be 30 days, several months, or longer. Your plan determines the actual deadline.
Check this clause before resigning. The deadline can determine whether you have enough time to arrange the exercise cost and applicable tax.
Do ESOPs Guarantee Wealth?
ESOPs create potential financial upside through company ownership, while the eventual outcome depends on vesting, exercise, taxation, company value, and liquidity.
Before treating an ESOP grant as part of your financial plan, understand:
- Vesting schedule
- Exercise cost
- Tax treatment
- Liquidity routes
- Post-resignation exercise window
The company side also involves ongoing equity administration. This includes cap table management, ESOP administration, Ind AS 102 reporting, employee communication, and compensation benchmarking.
The employee side comes down to understanding what you have received, what it costs to convert the option into shares, and how those shares can eventually become cash.
About Hissa
Hissa helps Indian companies manage equity across the full lifecycle. Its platform supports cap table management, ESOP administration, employee equity workflows, and compliance processes.
Hissa also supports employee tax and exercise workflows, while its dedicated Hissa Fund provides a potential pre-IPO liquidity route for eligible employee shares.
Hissa works with 200+ companies and manages $3.5 billion in ESOP grants.
The Hissa Fund is a $35 million SEBI-registered Category II Alternative Investment Fund focused on ESOP liquidity.